

Over the last six months, Bentley Systems’s shares have sunk to $31.87, producing a disappointing 9.2% loss - a stark contrast to the S&P 500’s 16.9% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Bentley Systems, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Bentley Systems Not Exciting?
Despite the more favorable entry price, we don’t have much confidence in Bentley Systems. Here are three reasons why BSY doesn’t excite us, plus one stock we’d rather own.
1. Weak ARR Points to Soft Demand
While reported revenue for a software company can include low-margin items like implementation fees, annual recurring revenue (ARR) is a sum of the next 12 months of contracted revenue purely from software subscriptions, or the high-margin, predictable revenue streams that make SaaS businesses so valuable.
Bentley Systems’s ARR came in at $1.54 billion in Q2, and over the last four quarters, its year-on-year growth averaged 12.3%. This performance was underwhelming and suggests that increasing competition is causing challenges in securing longer-term commitments. 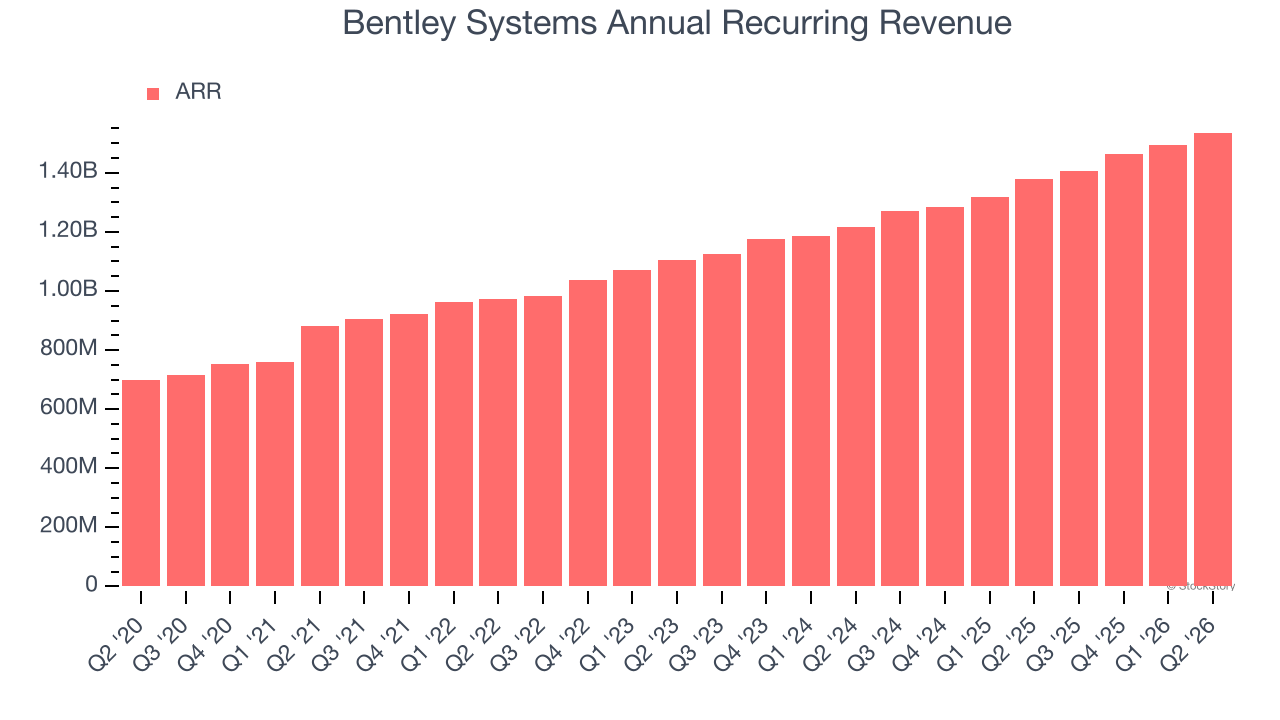
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Bentley Systems’s revenue to rise by 11.2%, close to its 13% annualized growth for the past five years. This projection is underwhelming and implies its newer products and services will not lead to better top-line performance yet.
3. Operating Margin in Limbo
While many software businesses point investors to their adjusted profits, which exclude stock-based compensation (SBC), we prefer GAAP operating margin because SBC is a legitimate expense used to attract and retain talent. This metric shows how much revenue remains after accounting for all core expenses — everything from the cost of goods sold to sales and R&D.
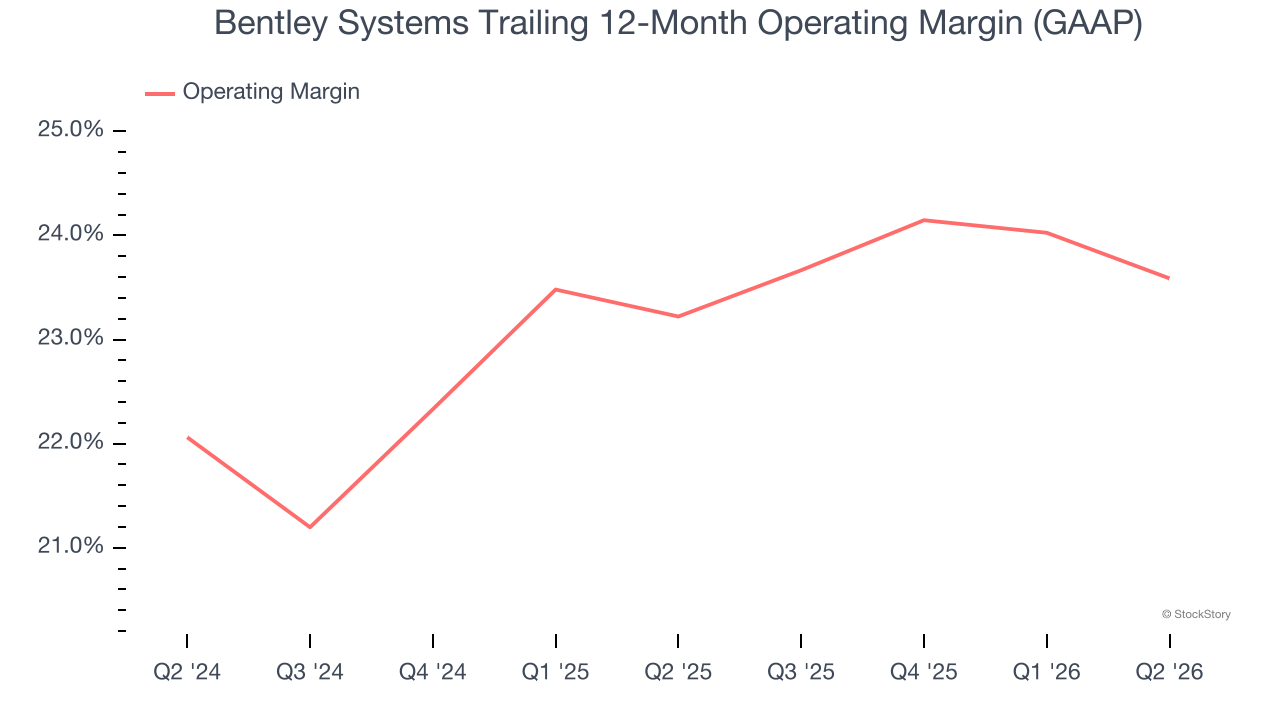
Analyzing the trend in its profitability, Bentley Systems’s operating margin might have fluctuated slightly but has generally stayed the same over the last two years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 23.6%.
Final Judgment
Bentley Systems’s business quality ultimately falls short of our standards. After the recent drawdown, the stock trades at 5.9× forward price-to-sales (or $31.87 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at one of our top software and edge computing picks.
Stocks We Would Buy Instead of Bentley Systems
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.