
What a time it’s been for Amneal. In the past six months alone, the company’s stock price has increased by a massive 47.7%, reaching $18.31 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Amneal, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Amneal Not Exciting?
Despite the momentum, we’re sitting this one out for now. Here are three reasons why AMRX doesn’t excite us, plus one stock we’d rather own.
1. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Amneal’s revenue to rise by 3.3%, a deceleration versus its 8.7% annualized growth for the past five years. This projection doesn’t excite us and implies its products and services will face some demand challenges.
2. EPS Barely Growing
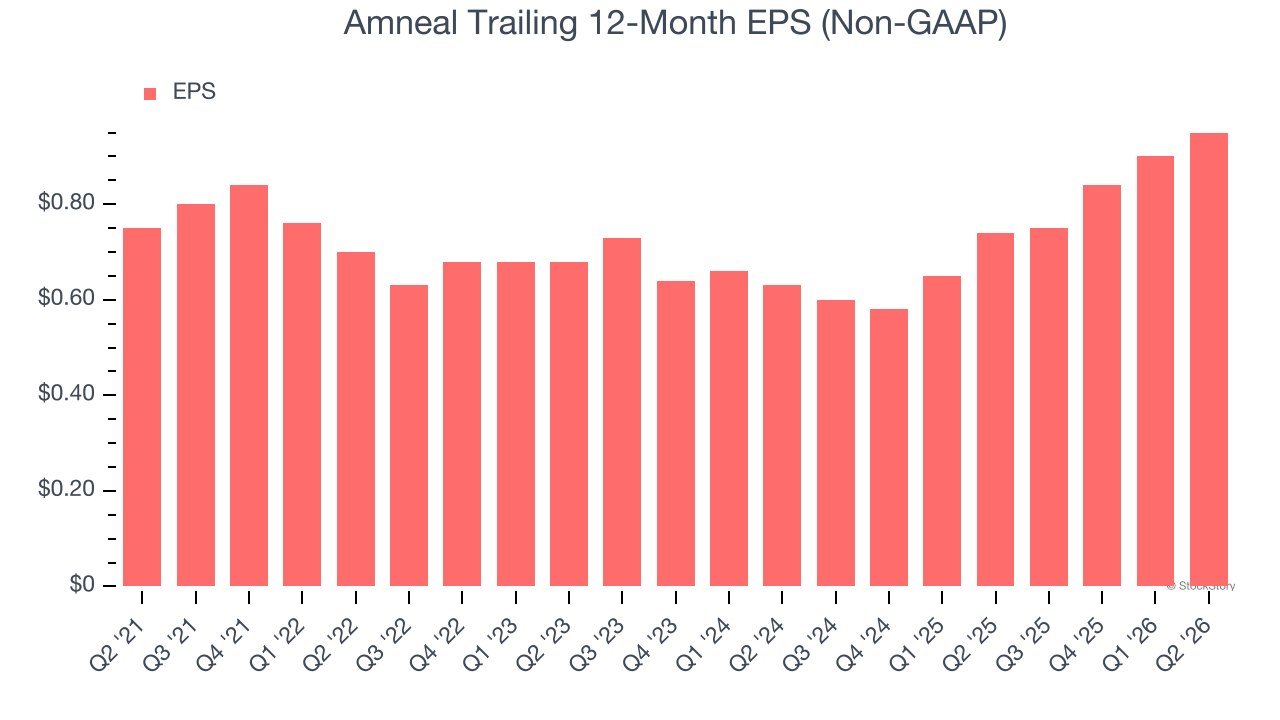
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Amneal’s EPS grew at an unimpressive 4.8% compounded annual growth rate over the last five years, lower than its 8.7% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Previous Growth Initiatives Haven’t Impressed
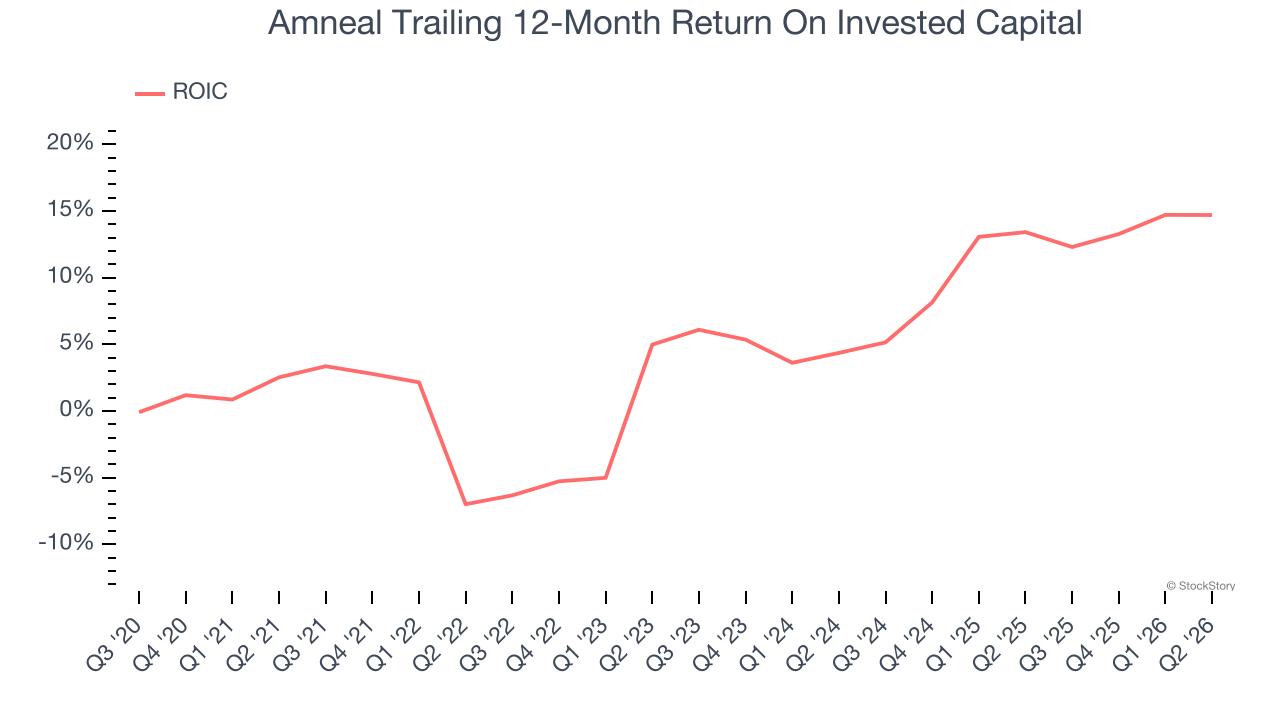
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Amneal historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 6.1%, somewhat low compared to the best healthcare companies that consistently pump out 25%+.
Final Judgment
Amneal isn’t a terrible business, but it isn’t one of our picks. After the recent surge, the stock trades at 18.1× forward P/E (or $18.31 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.